SoftSwiss and KA Gaming gain ground as leading supplier shares narrow in September
Pragmatic Play and Evolution Gaming retained the two largest shares of global operator content in September 2026, but both lost ground as SoftSwiss, KA Gaming, Spinomenal and several mid-ranking supplier groups strengthened their portfolio presence.
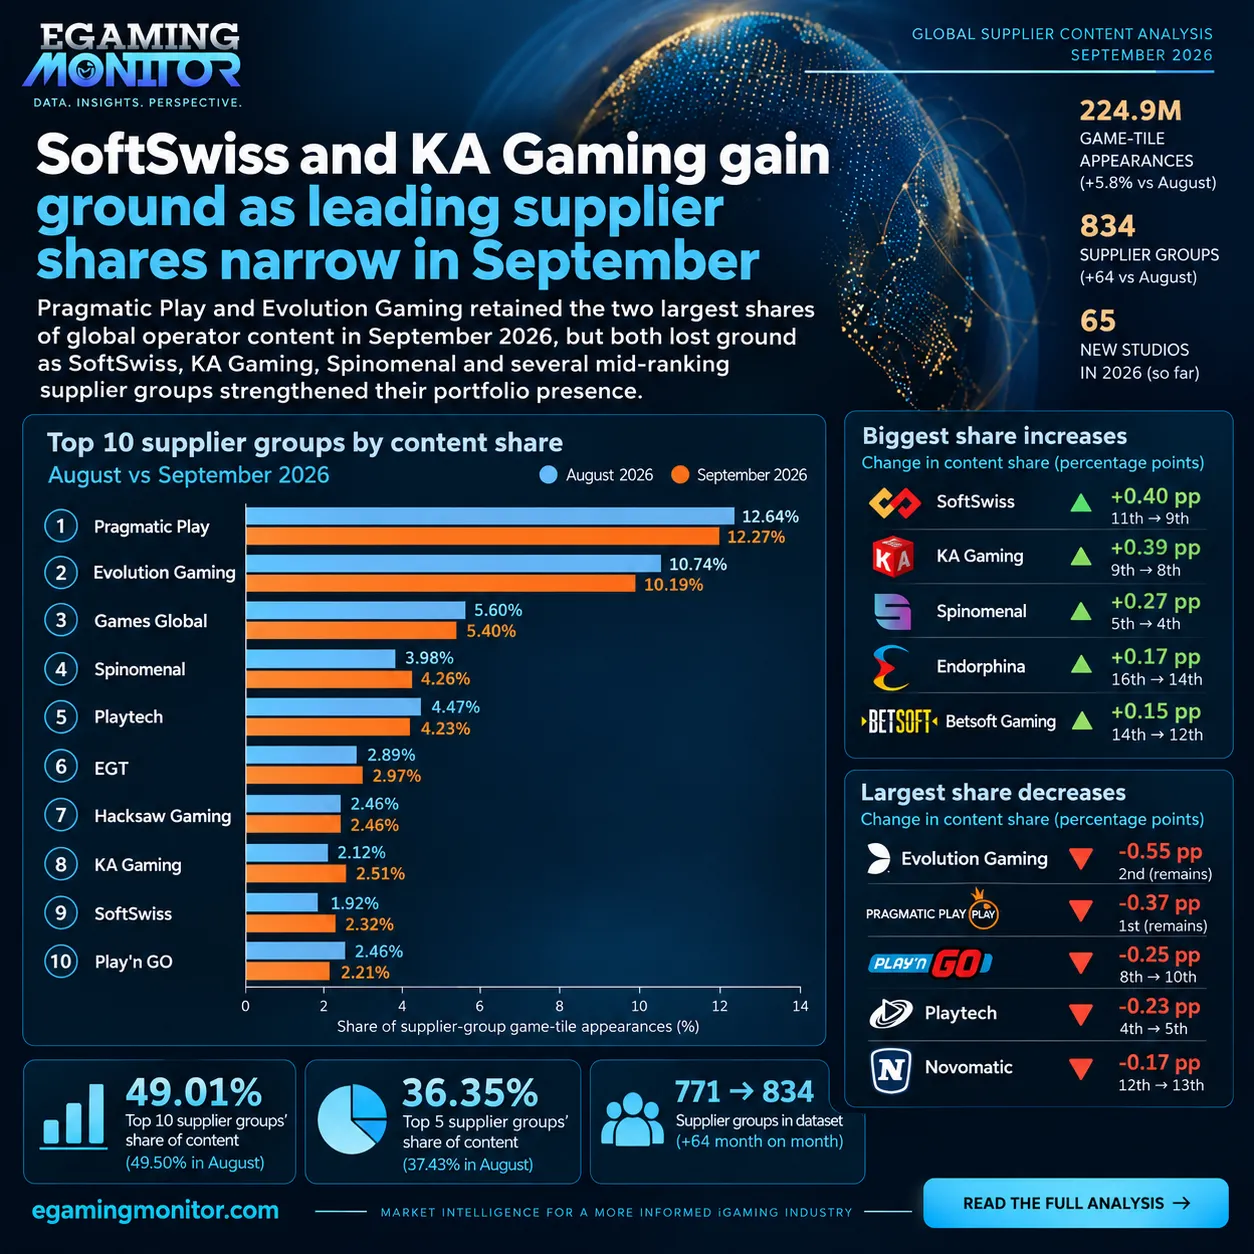
The latest egamingmonitor.com supplier-group analysis shows another month of relative stability at the very top of the global content market, but considerably more movement immediately below it. Pragmatic Play remained No.1 with 12.27% of recorded supplier-group game-tile appearances, followed by Evolution Gaming on 10.19% and Games Global on 5.40%.
The September dataset recorded approximately 224.9 million supplier-group game-tile appearances, up from 212.5 million in August. Because the overall monitoring volume increased, percentage share provides the cleaner month-on-month comparison.
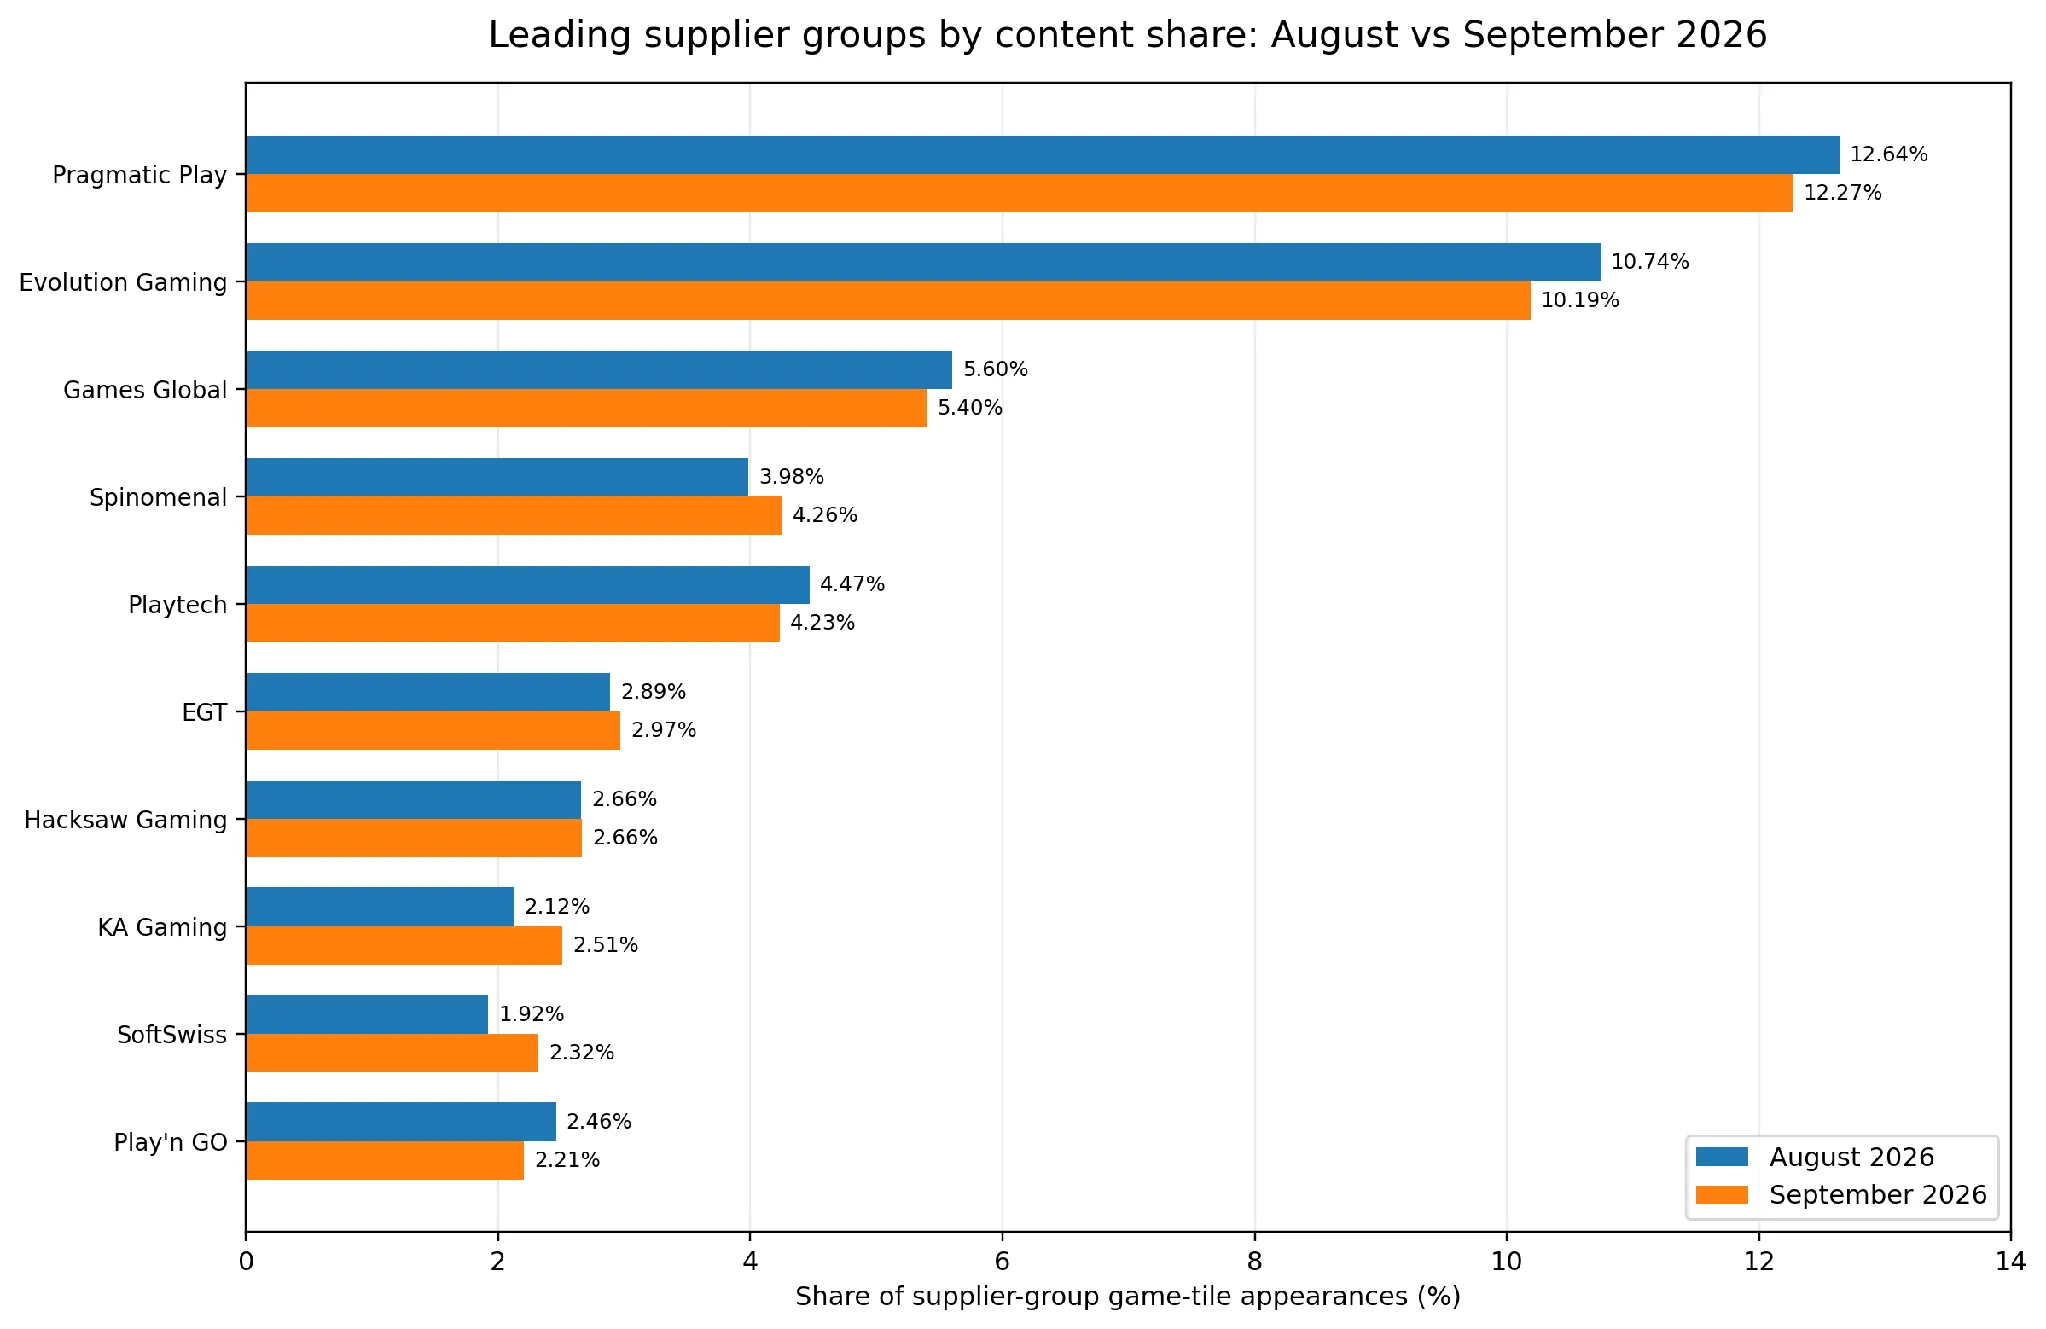
Figure 1. Leading supplier groups by content share, August versus September 2026.
Pragmatic Play remains No.1 as the top two both lose share
Pragmatic Play retained a clear global lead, but its content share fell from 12.64% in August to 12.27% in September, a decline of around 0.37 percentage points. Its absolute game-tile count still increased, from 26.86 million to 27.60 million, but not as quickly as the overall monitored market.
Evolution Gaming showed the same pattern more strongly. Its recorded appearances edged up from 22.83 million to 22.91 million, yet its share fell from 10.74% to 10.19% – a 0.55 percentage-point decline and the largest reduction among the leading supplier groups.
Together, the two largest supplier groups accounted for 22.46% of September content, down from 23.38% in August.
Spinomenal overtakes Playtech for fourth
Spinomenal was the strongest mover within the top five. Its share increased from 3.98% to 4.26%, lifting it from fifth to fourth place. Its recorded game-tile total rose from 8.47 million to 9.57 million.
Playtech slipped from fourth to fifth as its share declined from 4.47% to 4.23%, despite its absolute tile count remaining broadly stable. Games Global held third place but also lost share, falling from 5.60% to 5.40%.
SoftSwiss and KA Gaming record the biggest top-tier gains
SoftSwiss produced the largest percentage-point gain among September’s top 20 supplier groups. Its share climbed from 1.92% to 2.32%, moving it from eleventh to ninth place. Its recorded game-tile appearances increased from 4.08 million to 5.22 million.
KA Gaming was close behind, rising from 2.12% to 2.51% and moving from ninth to eighth. Spinomenal added around 0.27 percentage points, while Endorphina and Betsoft Gaming gained approximately 0.17 and 0.15 points respectively.
Play’n GO drops two places while Novomatic gives back August’s gain
Play’n GO moved in the opposite direction, falling from eighth to tenth as its share declined from 2.46% to 2.21%. The supplier’s absolute tile count also fell from 5.22 million to 4.96 million.
Novomatic, which had been the strongest top-20 share gainer in August, slipped from twelfth to thirteenth in September. Its share fell from 1.62% to 1.45%, reversing much of the previous month’s gain.
Light & Wonder also moved down two places, from thirteenth to fifteenth, while Evolution Gaming, Pragmatic Play, Playtech and Games Global all lost share despite remaining among the largest groups.
Jili Games continues its upward trend
Jili Games continued to strengthen, increasing its share from 1.07% to 1.15% and moving from eighteenth to seventeenth. That follows its move from twentieth to eighteenth in August and extends a sustained climb from 25th place in May.
Booming Games also entered the September top 20 at nineteenth, up from twenty-first, while Playson held twentieth place.
Key supplier movements
| Supplier group | August share | September share | Change | Aug rank | Sep rank |
| SoftSwiss | 1.92% | 2.32% | +0.40 pp | 11 | 9 |
| KA Gaming | 2.12% | 2.51% | +0.39 pp | 9 | 8 |
| Spinomenal | 3.98% | 4.26% | +0.27 pp | 5 | 4 |
| Endorphina | 1.15% | 1.32% | +0.17 pp | 16 | 14 |
| Betsoft Gaming | 1.45% | 1.60% | +0.15 pp | 14 | 12 |
| Evolution Gaming | 10.74% | 10.19% | -0.55 pp | 2 | 2 |
| Pragmatic Play | 12.64% | 12.27% | -0.37 pp | 1 | 1 |
| Play’n GO | 2.46% | 2.21% | -0.25 pp | 8 | 10 |
| Playtech | 4.47% | 4.23% | -0.23 pp | 4 | 5 |
| Novomatic | 1.62% | 1.45% | -0.17 pp | 12 | 13 |
The long tail broadens further and some new studios to watch out for
The top ten supplier groups accounted for 49.01% of September’s recorded content, down from 49.50% in August. The top five fell more noticeably, from 37.43% to 36.35%.
The latest workbook contains 834 supplier groups (1,197 studio brands) with recorded September appearances, compared with 770 (1,063 studio brands) in August. Combined with the lower top-ten and top-five shares, that points to a broader spread of content across the long tail even as the market leaders remain firmly established.
New this month is our ‘Top10 new suppliers to watch’ list below. This ranks the best new performers in content share terms of suppliers that were added to our dataset in 2026.
Portfolio presence, not direct revenue market share
The figures measure how frequently games associated with each supplier group appeared across operator websites monitored by egamingmonitor.com. They should therefore be interpreted primarily as an indicator of content distribution and portfolio visibility.
Share movements can reflect new integrations, game launches, promotional placement, operator portfolio decisions and changes in the volume of pages or game tiles captured during the monitoring period. When combined with filters such as operator size and position on page, the full egamingmonitor.com dataset can also be used to develop a closer proxy for commercial market share.
Source and methodology: egamingmonitor.com global supplier-group content monitoring data, August and September 2026. The September dataset recorded approximately 224.9 million supplier-group game-tile appearances. Supplier share is calculated from the frequency with which games from each supplier group appear across nearly 5,000 monitored operator websites. For comprehensive supplier, studio, game and operator-level analysis by market, contact egamingmonitor.com.
FAQs
Which supplier group had the largest share of casino content in September 2026?
Pragmatic Play remained the largest supplier group in September 2026, accounting for 12.27% of recorded supplier-group game-tile appearances across the operator websites monitored by egamingmonitor.com. Evolution Gaming ranked second with 10.19%.
Which supplier groups gained the most content share in September 2026?
SoftSwiss recorded the largest gain among the leading supplier groups, increasing from 1.92% in August to 2.32% in September, a rise of 0.40 percentage points. KA Gaming followed closely, increasing from 2.12% to 2.51%, while Spinomenal rose from 3.98% to 4.26%.
Which supplier groups lost the most share between August and September 2026?
Evolution Gaming recorded the largest percentage-point decline among the leading suppliers, falling from 10.74% to 10.19%. Pragmatic Play also declined, from 12.64% to 12.27%, while Play’n GO fell from 2.46% to 2.21%.
How concentrated is the global casino content market?
The top 10 supplier groups accounted for approximately 49.01% of recorded content in September 2026, down slightly from 49.50% in August. The top five accounted for 36.35%, compared with 37.43% a month earlier, suggesting a modest broadening of content across smaller supplier groups.